Redemption is a debtor right; an auction bid is a sale transaction
Model UCC § 9-623 gives specified parties a right to redeem by tendering the required secured obligations and expenses before disposition, a contract for disposition, or acceptance in satisfaction. The debtor does not win redemption by outbidding anyone; the right is exercised by satisfying the statutory tender requirement in time.
At a public disposition, the debtor may have an opportunity to bid, but the auction has its own registration, deposit, payment, and title rules. A bid can fail, another bidder can win, or the auction can be postponed. Those uncertainties are not part of redemption.
Compare the cash requirement carefully
A redemption quote can reflect the full accelerated secured obligation plus allowed expenses. The winning auction price may be lower, but a borrower who wins at auction may still face the pre-existing deficiency accounting depending on how the transaction and state law work; buying the collateral is not automatically a settlement of the old debt.
Before bidding, ask how the creditor will apply the auction proceeds and whether the buyer must pay taxes, buyer fees, storage, or other auction charges. Do not assume that paying the auction house replaces every obligation under the prior contract.
The notice tells you whether the sale is truly public
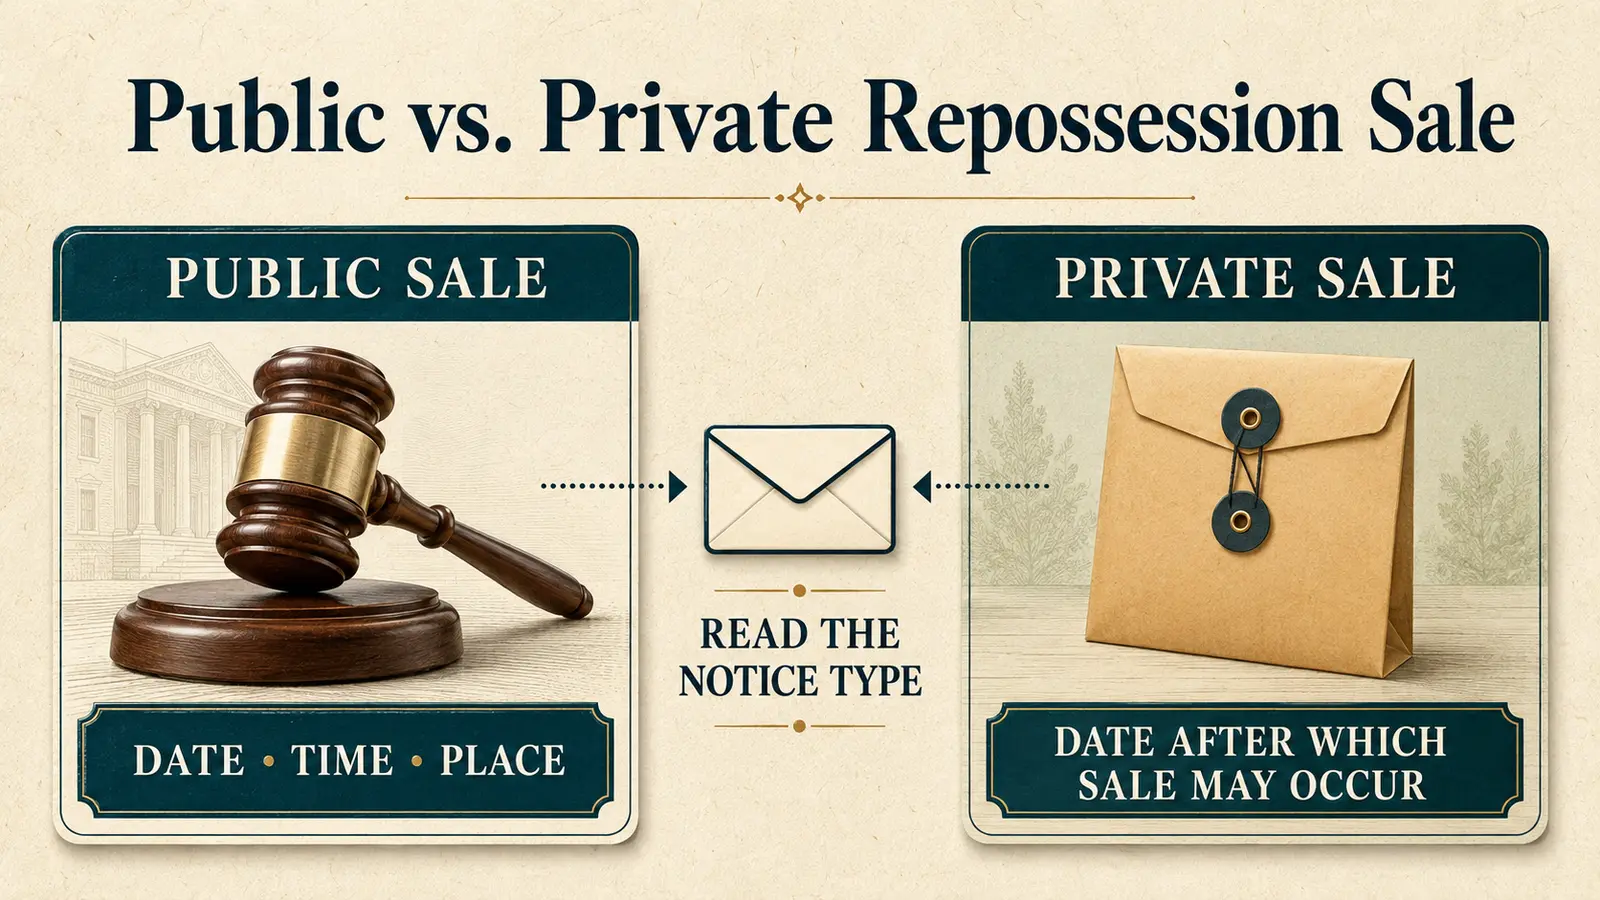
Article 9 distinguishes public and private disposition. A consumer-goods notice for a public disposition should provide the time and place so the debtor can attend or bid if permitted. A notice that merely mentions “auction” does not tell you whether the sale qualifies as public under the governing state law.
If the sale is online, dealer-only, or restricted, investigate the access terms. Courts may examine whether the chosen method and marketing were commercially reasonable. Save the auction listing, bidder requirements, photographs, condition report, and result.
Redemption timing can end before the gavel falls
The model rule ends redemption when the secured party has disposed of the collateral or entered into a contract for its disposition, among other events. Depending on how the sale is structured, waiting until the auction’s closing moment can be too late.
Ask the creditor for a written redemption deadline and payment instructions. If you intend to redeem, do not rely on the auction company’s calendar as the only source of timing.
A debtor purchase can complicate the deficiency math
If the debtor becomes the auction buyer, there are two sets of numbers: the price paid to acquire the vehicle and the application of sale proceeds to the old secured obligation. Keep invoices and account statements from both sides of the transaction.
Model § 9-615 contains special calculation language when disposition is made to the secured party, a related person, or a secondary obligor at a price significantly below a qualifying market measure. That provision does not mean every low sale to every buyer automatically resets the deficiency, but it is a reason to identify who bought the vehicle.
Choose the path based on legal effect, not the headline price
Redemption provides certainty if the tender can be completed and the right is still open; an auction bid may offer a lower acquisition price but carries bidding and sale risks. State law can also add reinstatement rights that change the comparison entirely.
The correct first question is therefore not “Which price is cheaper?” It is “Which legal mechanism is available, what does it do to the old contract and deficiency, and what deadline controls it?”
Redemption is a pre-disposition right; an auction purchase is a new transaction
Model UCC § 9-623 allows redemption only before the secured party has collected, disposed of the collateral or entered a contract for its disposition, or accepted the collateral under § 9-620. The redeeming party must tender fulfillment of the secured obligations plus the expenses and attorney’s fees described by the statute where applicable. That is legally different from appearing at a public auction and competing as a bidder after the creditor has chosen the sale route.
An auction purchase can carry buyer registration rules, deposits, buyer fees, title-processing steps, and the risk that another bidder wins. It also does not automatically erase a preexisting deficiency issue unless the sale proceeds and account application actually produce that result. Before relying on a “buy it back” plan, confirm whether the sale is public, whether consumers may bid, what payment form is accepted, and exactly when registration closes.
Do not let the sale date silently end the option you meant to use
If redemption is the intended path, request a written redemption quote early enough to verify payoff components and payment instructions. The disposition notice may identify the earliest sale time, but state law can add different requirements and a private sale may be described by an earliest date rather than a single auction hour. Save the quote request and response because a late or incomplete quote can become part of the timeline even though it does not automatically extend the statutory right.
Frequently asked questions
- Is bidding at the auction the same as redeeming the car?
- No. Redemption is a debtor right exercised before the sale by paying the full secured obligation plus expenses; an auction bid is a sale transaction at whatever the vehicle brings. They differ in timing, paperwork, and legal effect.
- Which is cheaper?
- Not always the auction. Compare the cash requirements carefully — redemption is the full payoff, but an auction purchase plus fees, and the effect on the remaining deficiency, can end up higher or lower depending on the sale price.
- Can the sale date end my redemption right without warning?
- Yes. Redemption timing can close before the gavel falls — once disposition happens or the secured party contracts for it. Confirm the exact cutoff in the notice rather than assuming it runs to auction day.
Sources checked for this page
- UCC § 9-623 — Right to redeem collateralModel redemption right before disposition, collection, or acceptance.
- UCC § 9-610 — Disposition of collateral after defaultModel UCC text for public/private disposition and commercial reasonableness.
- UCC § 9-614 — Contents of notification: consumer-goods transactionModel consumer-goods disposition notice rules and safe-harbor form.
- UCC § 9-615 — Application of disposition proceeds; deficiency and surplusModel rules for applying sale proceeds and calculating deficiency/surplus.
- UCC § 9-627 — Commercial reasonablenessModel guideposts for commercially reasonable disposition.